
What is notes receivable?
Periodic interest accrued is recorded in Interest Revenue and Interest Receivable. The following example uses months but the calculation could also be based on a 365-day year. The examples provided account for collection of the note in full on the maturity date, which is considered an honored note. But what if the customer does not pay within the specified contract length?
Notes Receivables – Definition, Importance, Example, and Classification
The Bullock Company’s journal entries for 1 November 2019, 31 December 2019, and 31 January 2020 are shown below. It is possible to combine the previous two entries by debiting Notes Receivable and crediting Sales. Together, the principal and interest portions represent the note’s maturity value. In some industries, it is common for a seller to insist on a note rather than an open account for certain types of sales. The note presents all terms and conditions transparently to remove any possible misunderstandings between the parties in the future.
How is Interest on a Note Recorded?
- The firm’s year-end is 31 December, and the note will mature on 31 January 2020.
- Terrance Inc. agrees to grant Dino-Kleen a longer period of time to pay the invoice in exchange for 5% interest.
- Although it may seem peculiar to record interest revenue on defaulted notes receivable, the Zoe Company is still obligated to pay both the interest and the principal.
- They represent an asset to the company, indicating amounts owed to them by debtors.
- The journal entry will follow if a company pays another party directly in exchange for a note receivable.
Notes payable are financial documents that represent different perspectives in a credit transaction. So, notes receivable appear as assets on the creditor’s or payee’s balance sheet, whereas notes payable appear as liabilities on the debtor’s or maker’s balance sheet. In accounting , notes receivable are recorded as an asset on the balance sheet. To be precise, a payee records a note receivable as an asset, representing the principal owed by the customer.
Would you prefer to work with a financial professional remotely or in-person?
- Unlike usual trading balances and credits, notes receivable balances come with additional terms.
- In some cases, the term of the note is expressed in days, and the exact number of days should be used in the interest computation.
- Sometimes a company receives a note when it sells high-priced merchandise; more often, a note results from the conversion of an overdue account receivable.
- Rather than using Interest Receivable for the one day of interest in April, we record it as part of the cash payment, skipping the step of first entering it in the receivable.
- The payee is the party that provides the loan, also known as the borrower.
- It is not unusual for a company to have both a Notes Receivable and a Notes Payable account on their statement of financial position.
Accounts Receivable is a normal business transaction for between a company and its customer. The intent is for the debt to be settled in the normal course of business, usually in 30 days (depending on the terms of the account.) It typically does not have an interest rate. Interest on a note receivable is calculated by multiplying the principal balance of the note by the interest rate and by the number of days that have elapsed since the last interest payment was made divided by 365. The journal entry for interest on a note receivable is to debit the interest income account and credit the cash account. There are several elements of promissory notes that are important to a full understanding of accounting for these notes.
- Each Square account has potentially different terms based on its history and trends.
- If Anchor used ASPE, there would be a choice between the effective interest method and the straight-line method.
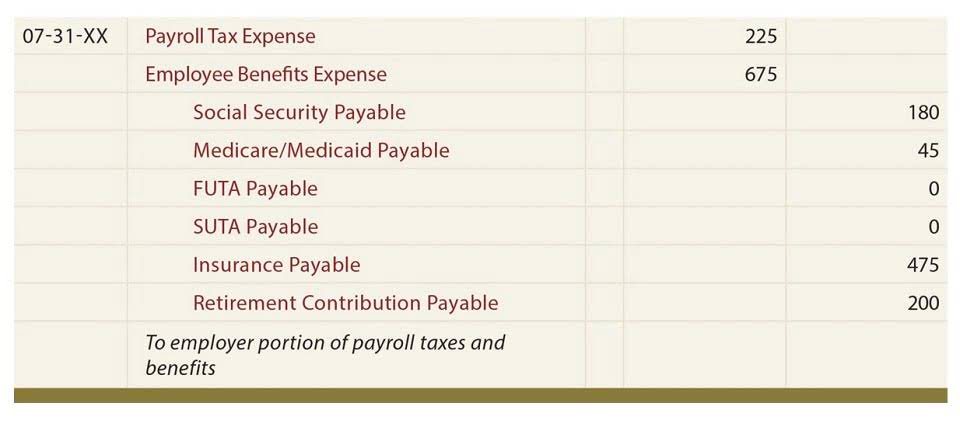
- Accruing tax liabilities in accounting involves recognizing and recording taxes that a company owes but has not yet paid.
- Note receivable from ABC LLC carried 5% simple interest rate payable annually while the one from DEF Inc. carried 8% interest compounded monthly.
- All of our content is based on objective analysis, and the opinions are our own.
Also, the company may be able to sell the note to a bank or other financial institution. You are the owner of a retail health food store and have several large companies with whom you do business. Many competitors in your industry are vying for your customers’ is note receivable an asset business. For each sale, you issue a notes receivable to the company, with an interest rate of 10% and a maturity date 18 months after the issue date. The difference between a short-term note and a long-term note is the length of time to maturity.
Are notes receivable, debit, or credit?
A note’s maturity date is the date at which the principal and interest become due and payable. Notes receivables are written promissory notes which give the holder or bearer the right to receive the amount mentioned in the agreement. Sometimes accounts receivables are converted into notes receivables to allow the debtors to pay the balance. However, for any receivables due in less than one year, this interest income component is usually insignificant.
Many business calculators require the use of a +/- sign for one value and no sign (or a positive value) for the other to calculate imputed interest rates correctly. Consult your calculator manual for further instructions regarding zero-interest note calculations. FV is the payment at the end of six months’ time (future value) of $5,000.

This record represents the complete settlement with cash upon maturity. It removes the notes receivable from Company ABC for the original amount and documents interest earnings based on the duration the note remained outstanding. They grant the holder the entitlement to receive the specified amount stipulated in the contractual agreement. These notes essentially serve as written assurances of the debtor to remit cash to another party by a designated future date. Characteristically, notes are similar to loans because they come with interest and principal amounts. Among these, one customer with a $5,000 wants to convert the balance to a note receivable.
Since the note is void but the customer did not pay or make arrangements for a new note, the only account remaining to record what is owed is Accounts Receivable. Situation 2a – The company receives another note from the customer for the principal of the first note plus the interest. The payee is typically a business or creditor expecting payment on a specific date. This examines a note from the lender’s perspective; see Current Liabilities for an in-depth discussion on the customer’s liability with a note (payable).